Student Debt: Actionable Steps to Reduce Your Loan Burden
Effectively reducing your student loan burden involves a combination of strategic repayment plans, refinancing options, and proactive financial management to minimize interest and accelerate debt payoff.
Navigating the complexities of student loan burden can feel overwhelming, but with the right strategies, you can significantly reduce your financial obligations. This article will guide you through actionable steps, from understanding your loans to implementing effective repayment plans, ensuring you gain control over your financial future.
Understanding your student loans: the crucial first step
Before you can effectively tackle your student debt, it’s essential to have a clear understanding of what you owe. Many borrowers are unaware of the nuances of their loans, which can hinder their ability to make informed decisions about repayment. Knowing the type of loans you have, their interest rates, and your current loan servicer is fundamental to developing a successful debt reduction strategy.
Federal versus private loans
Student loans typically fall into two main categories: federal and private. Federal student loans are issued by the U.S. Department of Education and come with various borrower protections and repayment options. Private student loans, on the other hand, are offered by banks, credit unions, and other financial institutions, often with fewer flexible repayment terms.
- Federal loans: Often offer income-driven repayment plans, deferment, forbearance, and potential for loan forgiveness. Interest rates are generally fixed.
- Private loans: Terms and conditions vary widely by lender. Interest rates can be fixed or variable, and borrower protections are typically limited.
- Consolidation: Federal loans can be consolidated into a Direct Consolidation Loan, which might simplify payments but could extend the repayment period.
Identifying whether your loans are federal or private will dictate which strategies are available to you. For instance, federal loan benefits like income-driven repayment plans are not typically available for private loans. Understanding these distinctions is the bedrock of any sound repayment strategy.
Interest rates and loan servicers
The interest rate on your loans significantly impacts the total amount you will repay. Higher interest rates mean more money accrues over time, making it harder to reduce your principal balance. It’s also crucial to know who your loan servicer is, as they are your point of contact for all repayment-related inquiries.
- Fixed vs. variable rates: Fixed rates remain constant, providing predictable payments. Variable rates can fluctuate with market conditions, potentially increasing your monthly payment.
- Loan servicers: Companies like Nelnet, Great Lakes, or Sallie Mae manage your loans. They process payments, offer repayment plan options, and provide customer support.
- Accessing loan information: You can find details about your federal loans on the National Student Loan Data System (NSLDS), and private loan information directly from your lender or credit report.
By thoroughly understanding your loans, including their type, interest rates, and servicers, you empower yourself to navigate the student debt landscape with confidence. This foundational knowledge is indispensable for taking effective steps toward reducing your loan burden.
Strategic repayment plans: choosing the right path
Once you have a clear picture of your loans, the next critical step is to select a repayment plan that aligns with your financial situation and goals. The right plan can significantly impact how quickly and efficiently you pay off your debt, potentially saving you thousands of dollars in interest.
Federal loan repayment options
Federal student loans offer a variety of repayment plans designed to accommodate different financial circumstances. These plans can be broadly categorized into standard, extended, graduated, and income-driven repayment (IDR) plans.
- Standard repayment plan: Fixed monthly payments over 10 years. This plan typically results in the lowest total interest paid.
- Extended repayment plan: Fixed or graduated payments over up to 25 years. This lowers monthly payments but increases total interest.
- Graduated repayment plan: Payments start low and increase every two years, over 10 to 25 years.
- Income-driven repayment (IDR) plans: Payments are based on your income and family size, typically 10-20% of your discretionary income. Any remaining balance after 20 or 25 years may be forgiven, though it could be taxable.
Choosing an IDR plan can be particularly beneficial if your income is low relative to your debt. These plans can prevent default and offer a safety net during financial hardship. However, they can also extend the repayment period and potentially increase the total amount of interest paid over the life of the loan.
Private loan repayment strategies
Private loans generally offer fewer flexible repayment options compared to federal loans. However, you still have strategies to consider for managing them effectively. These often involve direct negotiation with your lender or exploring refinancing options.
- Negotiating with lenders: If you’re struggling, contact your private lender to discuss potential options like temporary payment reductions or forbearance. Success varies by lender and your financial situation.
- Aggressive repayment: If possible, making extra payments on your private loans, especially those with high interest rates, can significantly reduce your principal faster.
- Bi-weekly payments: Paying half your monthly payment every two weeks results in one extra payment per year, accelerating your payoff without a drastic increase in your budget.
Carefully evaluating each repayment option and understanding its implications for your financial future is crucial. The goal is to find a plan that makes your payments manageable while minimizing the overall cost of your loans. Do not hesitate to use online calculators or speak with a financial advisor to compare scenarios.
Refinancing and consolidation: lowering your interest rates
Refinancing and consolidation are powerful tools that can help reduce your student loan burden by potentially lowering your interest rate or simplifying your payments. While often used interchangeably, these two concepts have distinct applications, especially concerning federal and private loans.
Understanding federal loan consolidation
Federal loan consolidation allows you to combine multiple federal student loans into a single new loan, known as a Direct Consolidation Loan. This process simplifies your payments by giving you just one loan servicer and one monthly bill. It can also extend your repayment period, which lowers your monthly payment but may increase the total interest paid.
- Simplified payments: One monthly payment instead of several, making budgeting easier.
- Access to new repayment plans: Consolidation can sometimes make you eligible for income-driven repayment plans or public service loan forgiveness that you weren’t eligible for before.
- Interest rate: The new interest rate is the weighted average of your previous loans’ rates, rounded up to the nearest one-eighth of a percent. It does not necessarily lower your interest rate.
Consolidation can be particularly beneficial for borrowers who want to streamline their finances or gain access to federal loan benefits. However, it’s important to weigh the pros and cons, as extending the loan term can lead to paying more interest over time.
Private student loan refinancing
Refinancing involves taking out a new private loan to pay off one or more existing student loans, whether federal or private. The primary goal of refinancing is usually to secure a lower interest rate, which can significantly reduce your monthly payments and the total cost of your loan over time.
- Lower interest rates: If you have good credit and a stable income, you may qualify for a lower interest rate, especially if market rates have dropped or your credit score has improved since you first took out your loans.
- One monthly payment: Similar to consolidation, refinancing combines multiple loans into a single payment.
- Loss of federal benefits: Refinancing federal loans into a private loan means forfeiting valuable federal protections, such as income-driven repayment, deferment, forbearance, and loan forgiveness programs.
Refinancing is generally recommended for borrowers with private loans or those with federal loans who are confident they won’t need federal benefits. It’s crucial to shop around and compare offers from multiple lenders to find the best terms. Always use an interest rate calculator to see potential savings.
Aggressive payment strategies: accelerating your payoff
Beyond choosing the right repayment plan and exploring refinancing, implementing aggressive payment strategies can dramatically accelerate your student loan payoff. These methods focus on paying more than the minimum required, directly attacking your principal balance and reducing the overall interest accrued.
The debt snowball and debt avalanche methods
Two popular strategies for aggressive debt repayment are the debt snowball and debt avalanche methods. Both aim to motivate borrowers by providing a clear path to debt freedom, but they differ in their approach.
- Debt snowball: You pay off your smallest loan first while making minimum payments on all others. Once the smallest is paid, you apply that payment amount to the next smallest loan. This method provides psychological wins early on.
- Debt avalanche: You prioritize paying off the loan with the highest interest rate first, while making minimum payments on all other loans. This method saves you the most money on interest over time.
The choice between these two methods often depends on your personal finance philosophy. If you need quick wins to stay motivated, the debt snowball might be better. If saving the most money is your top priority, the debt avalanche is the more financially optimal choice.
Making extra payments and bi-weekly payments
Even small, consistent extra payments can make a significant difference. Every dollar paid above your minimum goes directly towards your principal, reducing the amount on which interest is calculated. Bi-weekly payments are another effective way to achieve this without feeling a drastic increase in your budget.
- Lump-sum payments: If you receive a bonus, tax refund, or inheritance, consider applying a portion directly to your student loans, especially those with high interest rates.
- Rounding up payments: If your payment is $247, round it up to $250. This small, consistent extra payment can add up over time.
- Bi-weekly payments: Paying half your monthly payment every two weeks results in 26 half-payments annually, equivalent to 13 full monthly payments instead of 12.
These aggressive payment strategies require discipline and a commitment to your financial goals. However, the long-term benefits of reducing your student loan burden faster, including significant interest savings and earlier financial freedom, make these efforts well worth it.
Leveraging income and expenses: maximizing your cash flow
Successfully reducing your student loan burden isn’t just about how you pay, but also about how much you can afford to pay. This involves strategically managing your income and expenses to free up more money for debt repayment. Maximizing your cash flow is a vital component of an effective debt reduction plan.
Budgeting and expense reduction
Creating and sticking to a detailed budget is the cornerstone of effective financial management. A budget allows you to see exactly where your money is going, identify areas where you can cut back, and reallocate those savings towards your student loans.
- Track your spending: Use apps, spreadsheets, or notebooks to monitor every dollar you spend for at least a month.
- Identify non-essential expenses: Look for areas like dining out, entertainment, or subscriptions that can be reduced or eliminated.
- Set realistic limits: Allocate specific amounts for different spending categories and stick to them.
- Automate savings: Set up automatic transfers from your checking to a savings account or directly to your loan principal.
Even small reductions in daily or weekly expenses can accumulate into substantial amounts over time. Every dollar saved from your budget is a dollar that can be directed towards your student loans, accelerating your path to debt freedom. Consistency is key in this endeavor.
Increasing your income streams
While cutting expenses is important, sometimes there’s a limit to how much you can trim. In such cases, focusing on increasing your income can provide a significant boost to your debt repayment efforts. This doesn’t necessarily mean getting a new job, but rather exploring additional income streams.
- Side hustles: Consider freelancing, gig economy jobs, or turning a hobby into a source of income. Platforms like Upwork, Fiverr, or local services can provide opportunities.
- Negotiate salary: If you’re employed, assess your market value and consider negotiating a higher salary or asking for a raise.
- Sell unused items: Declutter your home and sell items you no longer need through online marketplaces or consignment shops.
- Overtime or bonuses: If available, take advantage of overtime opportunities at your current job, or direct any work bonuses towards your loans.
By actively seeking ways to increase your income, you create more financial flexibility, allowing you to make larger or more frequent payments on your student loans. This dual approach of managing expenses and boosting income provides a robust framework for reducing your student loan burden effectively.
Exploring loan forgiveness programs and assistance
For some borrowers, particularly those with federal student loans and specific career paths, loan forgiveness programs can offer a path to significantly reduce or even eliminate their debt. Understanding these programs and their eligibility requirements is crucial, as they represent a powerful form of assistance.
Public service loan forgiveness (PSLF)
The Public Service Loan Forgiveness (PSLF) program is designed for full-time employees of qualifying non-profit organizations or government agencies. After making 120 qualifying monthly payments under a qualifying repayment plan, the remaining balance on your Direct Loans may be forgiven.
- Eligible employment: Work for federal, state, local, or tribal government; or a 501(c)(3) non-profit organization.
- Eligible loans: Only Direct Loans qualify. Other federal loans may become eligible after consolidation into a Direct Consolidation Loan.
- Qualifying payments: Must be made on time, for the full amount due, under a qualifying income-driven repayment plan.
PSLF has strict requirements, and borrowers must ensure they meet all criteria throughout their repayment journey. It is highly recommended to submit the Employment Certification Form annually to track progress and confirm eligibility. This proactive approach helps prevent surprises down the line.
Teacher loan forgiveness and other programs
Beyond PSLF, several other federal loan forgiveness and discharge programs cater to specific professions or circumstances. These can provide substantial relief for eligible borrowers, making it vital to research all available options.
- Teacher Loan Forgiveness: For teachers who work for five complete and consecutive academic years in a low-income school or educational service agency, up to $17,500 of eligible federal student loans may be forgiven.
- Total and Permanent Disability (TPD) Discharge: If you are deemed totally and permanently disabled, you may qualify to have your federal student loans discharged.
- Borrower Defense to Repayment: Forgiveness for borrowers whose schools engaged in misconduct, such as misrepresentation of job placement rates or program quality.
- Closed School Discharge: If your school closes while you are enrolled or soon after you withdraw, you may be eligible for a discharge of your federal student loans.
Understanding these potential avenues for loan forgiveness or discharge is a critical part of a comprehensive strategy to reduce your student loan burden. While not everyone will qualify, exploring these options can provide significant relief for those who do, aligning with specific career paths or unforeseen life events.
Maintaining financial wellness post-debt reduction
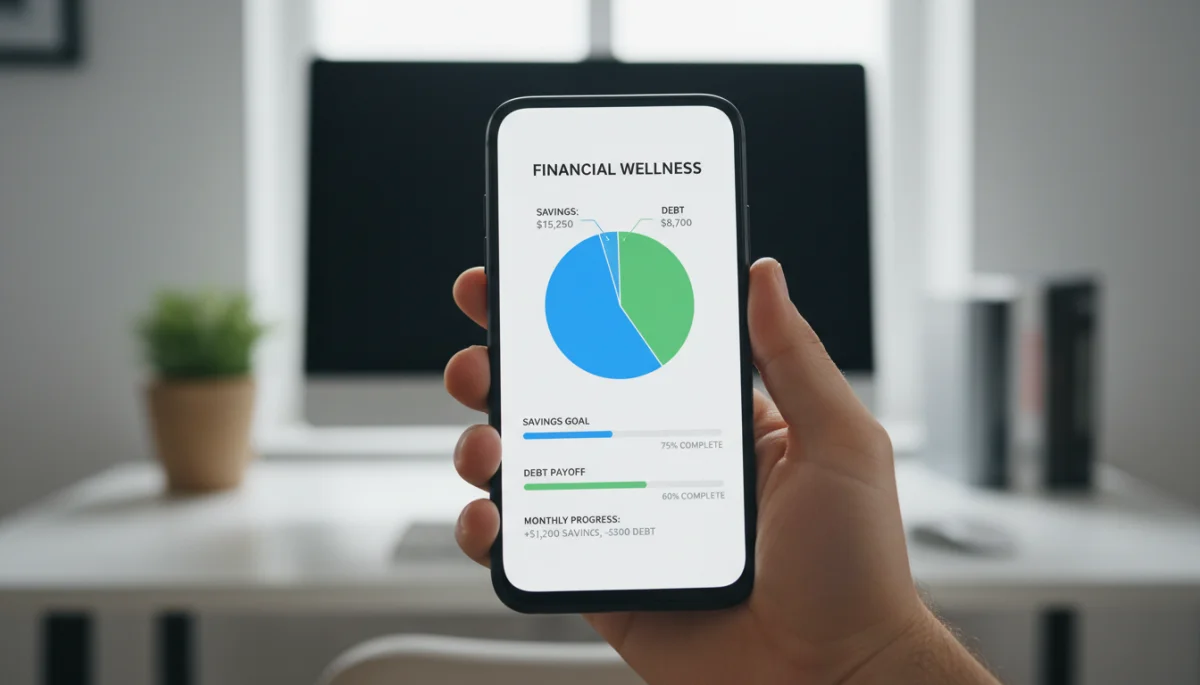
Achieving a reduced student loan burden is a significant accomplishment, but the journey doesn’t end there. Maintaining financial wellness post-debt reduction is crucial to prevent future debt accumulation and build a secure financial future. This involves establishing healthy financial habits and continuing to manage your money wisely.
Building an emergency fund
One of the most important steps after reducing your student debt is to build a robust emergency fund. This fund acts as a financial safety net, protecting you from unexpected expenses like job loss, medical emergencies, or car repairs, without having to resort to taking on new debt.
- Goal: Aim to save three to six months’ worth of essential living expenses.
- Separate account: Keep your emergency fund in a separate, easily accessible savings account, distinct from your checking account.
- Automation: Set up automatic transfers from your checking account to your emergency fund to build it consistently over time.
An emergency fund provides peace of mind and financial stability, ensuring that unforeseen circumstances don’t derail your hard-earned progress in debt reduction. It’s a foundational element of long-term financial health.
Investing for the future and continued savings
With your student loan burden lighter, you’ll have more disposable income available. This is an opportune time to shift your focus from debt repayment to building wealth through investing and continued savings. Early investment can lead to significant growth over time due to compounding.
- Retirement accounts: Maximize contributions to 401(k)s, IRAs, or Roth IRAs, especially if your employer offers a matching contribution.
- Diversified investments: Explore diversified investment portfolios that align with your risk tolerance and financial goals, such as mutual funds or exchange-traded funds (ETFs).
- Long-term savings goals: Continue saving for other significant life goals, such as a down payment on a home, a new car, or future education for yourself or your family.
By transitioning from a debt-focused mindset to a wealth-building one, you can leverage the financial discipline you developed during your debt reduction journey. This continuous commitment to smart financial practices ensures lasting financial wellness and a brighter future.
| Key Strategy | Brief Description |
|---|---|
| Understand Your Loans | Identify federal vs. private, interest rates, and servicers to tailor your approach. |
| Choose Repayment Plan | Select federal IDR plans or negotiate private loan terms to manage payments. |
| Refinance or Consolidate | Lower interest rates or simplify payments, carefully considering federal benefits. |
| Aggressive Payments | Utilize debt avalanche/snowball, extra, or bi-weekly payments to accelerate payoff. |
Frequently asked questions about student debt
Federal student loans are offered by the government with benefits like income-driven repayment plans and potential forgiveness. Private loans come from banks or credit unions, typically with fewer borrower protections and variable terms. Understanding this distinction is vital for choosing the right repayment strategy.
Yes, you can refinance federal student loans, but doing so converts them into private loans. This means you will lose federal benefits such as income-driven repayment options, deferment, and potential loan forgiveness programs. It’s a decision that requires careful consideration of the trade-offs.
An income-driven repayment (IDR) plan is a federal loan option that sets your monthly payment based on your income and family size. Payments can be as low as $0 per month, and any remaining balance after 20 or 25 years of payments may be forgiven. It’s designed to make payments affordable.
PSLF forgives the remaining balance on Direct Loans for borrowers who work full-time for qualifying non-profit or government organizations. You must make 120 qualifying monthly payments under a qualifying repayment plan. Strict eligibility rules apply, so consistent verification is important.
This depends on your loan’s interest rate and your risk tolerance. If your loan interest rate is high (e.g., above 7-8%), paying it off often yields a guaranteed return. If rates are lower, investing might offer higher potential returns, but with more risk. A balanced approach is often ideal.
Conclusion
Tackling your student loan burden requires a proactive and informed approach. By understanding the specifics of your loans, strategically choosing repayment plans, exploring refinancing or consolidation, and implementing aggressive payment methods, you can significantly reduce your debt. Furthermore, leveraging income and expense management, and investigating potential forgiveness programs, provides additional avenues for relief. Ultimately, developing sound financial habits will not only help you overcome student debt but also pave the way for long-term financial stability and success.
